Roof damage and insurance claims in Texas
A roof inspection explains the condition. Your policy and insurer determine how a covered claim is paid. Understand both before committing to the work.
Start with what you’ve noticed.
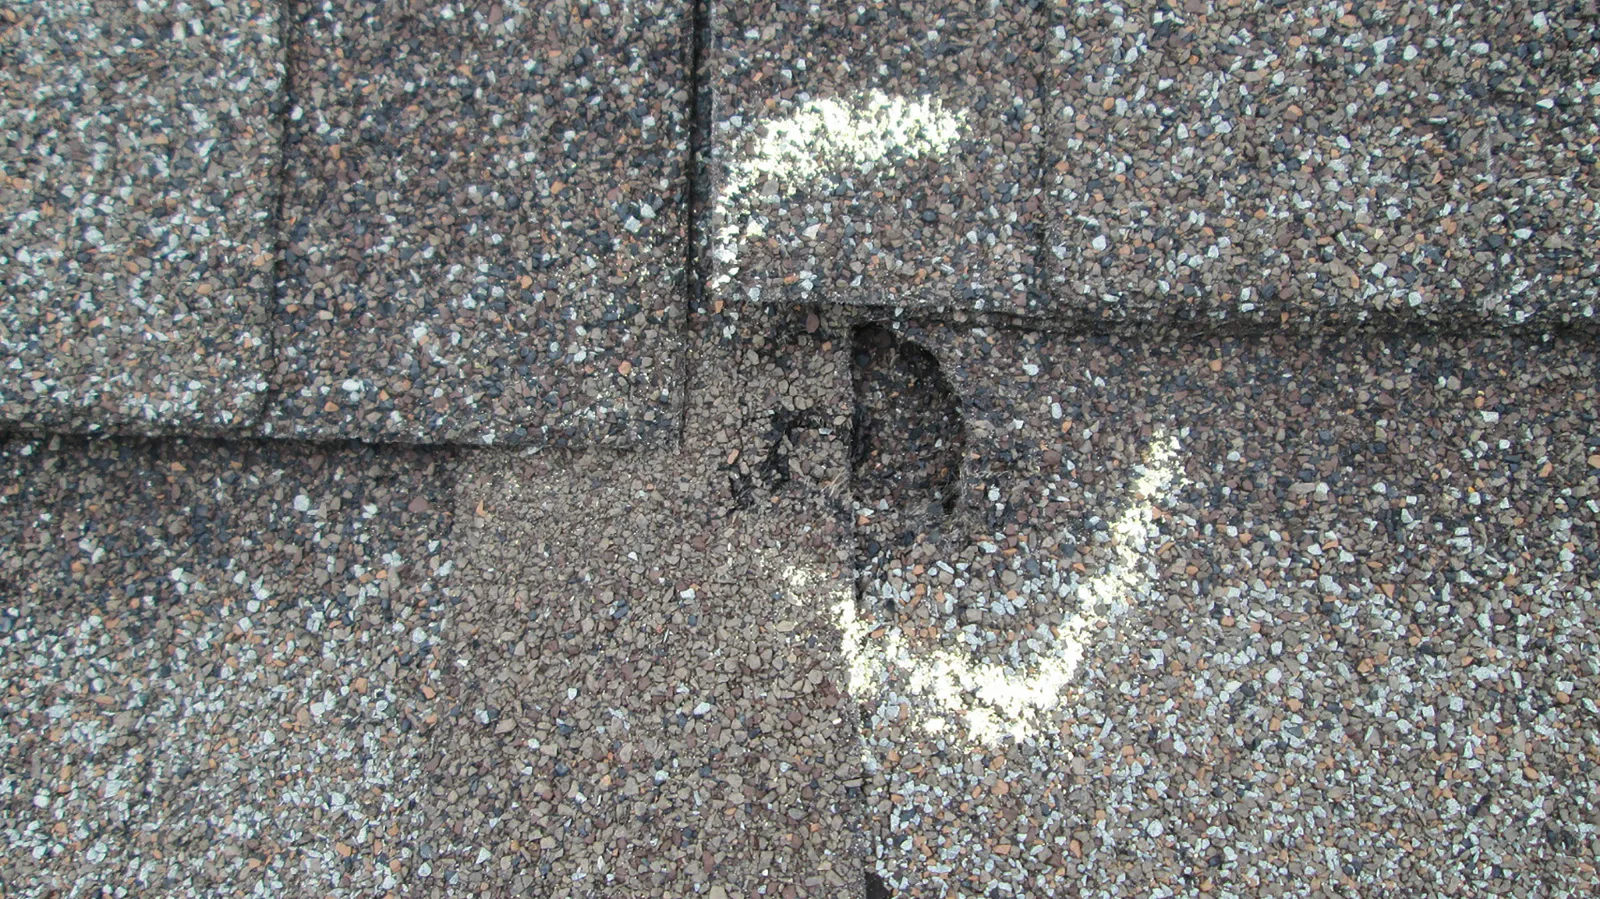
Understand the roof condition before the claim outcome
A damaged roof creates two related questions: what needs to be repaired, and what the insurance policy will pay. Keeping those questions clear makes the conversation easier. A roofer can explain the physical damage and proposed work; coverage comes from the policy and the insurer’s claim review.
The Texas Department of Insurance provides the consumer guidance linked here. Use the actual policy for deductibles, exclusions and payment terms, and ask the insurer to explain any part you do not understand.
Damage, deductible and payment method
The roof’s condition
An inspection distinguishes a damaged component from wear and looks at surrounding materials. Photos and a written scope help describe the work, but a damage observation alone does not establish insurance coverage.
The deductible
A covered loss still has the deductible stated in the policy. Know its dollar effect on the claim rather than assuming that the insurance payment is the entire project budget.
The settlement method
Actual cash value and replacement cost handle depreciation differently. The policy and the claim’s payment conditions determine whether additional money can be released after covered work is completed.
From a roof concern to an insurance decision
- 01
Protect people and limit exposure
Stay off the roof and away from wet electrical fittings or a sagging ceiling. If safe, record what you noticed and contact the appropriate service for immediate hazards or temporary protection.
- 02
Understand the damage and notify the insurer
Have the roof assessed and follow the policy’s notification requirements. Keep dates, photos, repair descriptions and receipts that are relevant to the claim.
- 03
Review the scope and payment terms
Compare the proposed roof work with the insurer’s explanation. Ask about differences in included work, deductible and depreciation before treating the first payment as the final project total.
Replacement cost and actual cash value
The Texas Department of Insurance roof replacement guide explains that an actual cash value policy accounts for depreciation. That can leave a larger share of replacement cost with the property owner. A replacement cost policy may pay in stages, with additional payment subject to its terms and completion of the covered work.
Ordinary aging and deterioration are different from a covered sudden loss. Review the policy’s treatment of the cause, the roof and any applicable exclusions rather than assuming that replacement is covered because the roof needs work.
Texas roof insurance FAQs
Does hail in a nearby weather report prove my roof claim?
No. A report describes an observed event at a recorded location. The storm-history tool can help identify a relevant date, but the roof condition and policy still need their own review.
Can I request an inspection before deciding whether to file a claim?
Yes. A free inspection can make the roof condition clearer. Keep any policy reporting requirements in mind while deciding the next step with your insurer.
What if the insurance scope and roofing proposal differ?
Ask each party to explain the specific items and quantities. Differences may involve materials, concealed damage, repair extent or policy terms; identify the actual disagreement instead of comparing only the final dollar amounts.
Get a closer look at the roof condition
Start with the roof itself. Request a free inspection and understand what work the condition calls for.
Call (469) 813-7720